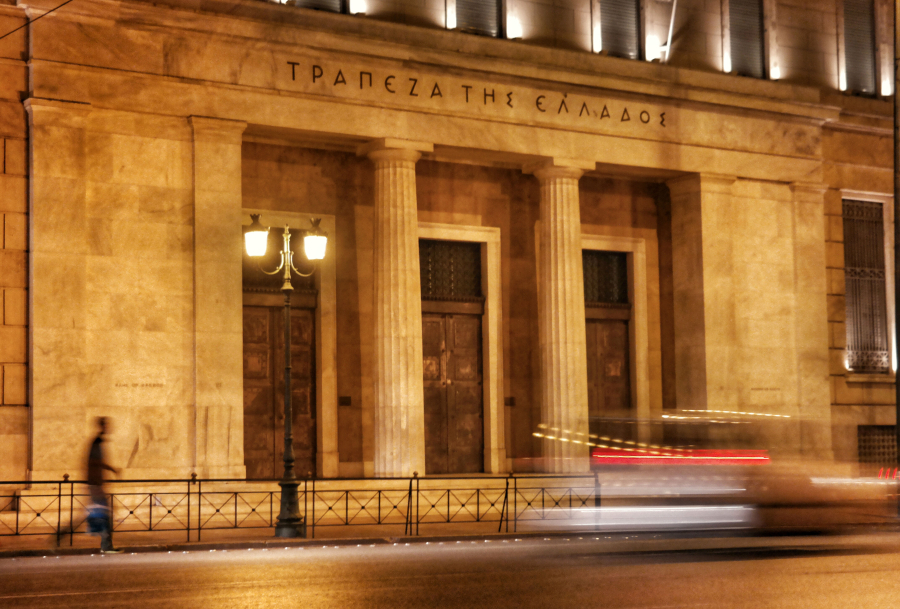
Greece's biggest banks are facing renewed scrutiny over their tax obligations as rising profits and plans for substantial shareholder payouts revive questions about financial privileges inherited from the country's debt crisis.
More than a decade after Greece's banking system required extensive financial support, its leading lenders have returned to profitability and resumed paying dividends. Yet they continue to benefit from tax arrangements established during the crisis, prompting debate over whether their contributions to public finances adequately reflect their recovery.
At the center of the controversy are deferred tax credits, or DTCs, which allow banks to recognize certain past losses and provisions as regulatory capital under a framework backed by the Greek state.
ΔΙΑΒΑΣΤΕ ΕΠΙΣΗΣ
Banks also continue to offset taxable profits against losses accumulated during the financial crisis, reducing their current corporate income-tax payments.
The arrangements helped stabilize Greece's banking system after years of recession, sovereign-debt restructuring and mounting loan defaults. But their continued use has become increasingly contentious as lenders generate billions of euros in earnings and prepare larger distributions to shareholders. Greek banks have accelerated the reduction of DTCs since 2025, including additional amortization linked to 29% of planned dividend payments.
The industry aims to reduce DTCs to between 20% and 30% of its core Tier 1 regulatory capital by the end of 2027, with the longer-term objective of eliminating them.
Critics argue that the pace of normalization should extend beyond profitability and shareholder returns to include the banks' tax contributions. Some have called on the Greek government to consider additional taxation of banking profits, potentially through a special levy designed to preserve lenders' capital adequacy.
Such proposals would raise difficult policy questions. Higher taxes could generate additional government revenue, but they could also reduce the capital available for lending, investment and shareholder distributions.
The debate also extends to bank fees and access to credit, with critics demanding lower charges and stronger financing for households and businesses.