
Inflation is squeezing Greek households. It is also proving lucrative for the government. A comparison of Greece’s draft budgets for 2026 and 2027 shows how higher-than-expected prices have helped generate billions of euros in additional tax revenue, particularly from value-added tax. The result is a widening fiscal surplus—and a debate over why more of the windfall isn’t being used for permanent tax cuts.
A year ago, Greece’s Finance Ministry expected 2026 tax revenue of €73.53 billion. It now forecasts €75.73 billion, an increase of roughly €2.2 billion from that initial estimate and €2.09 billion, or 2.8%, above the subsequent budget target.
VAT provides the clearest illustration. The government had budgeted €29.23 billion in VAT receipts for 2026. It now expects €30.78 billion, an overshoot of €1.55 billion. Taxes on goods and services more broadly are projected at €42.25 billion, €1.38 billion above target. Part of the explanation is inflation.
ΔΙΑΒΑΣΤΕ ΕΠΙΣΗΣ
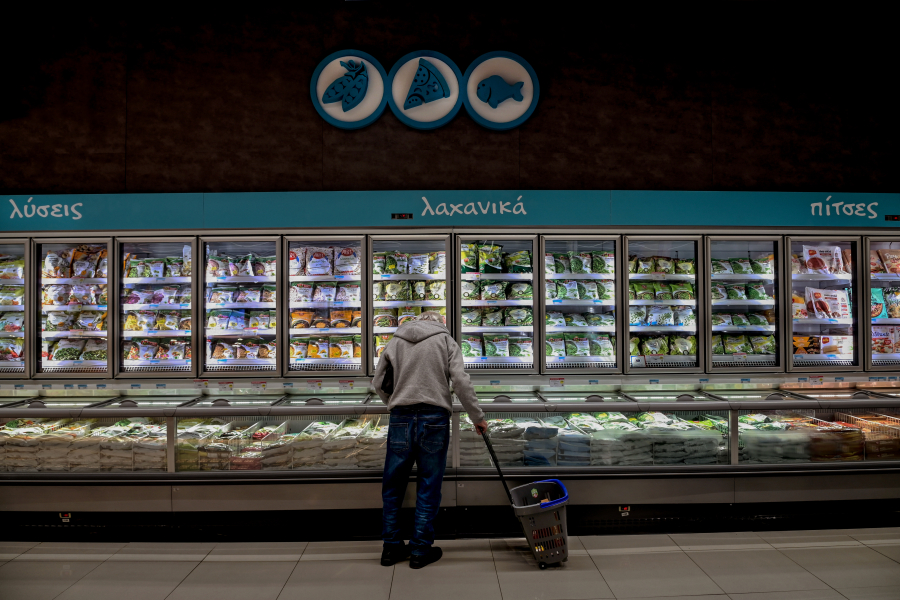
In October 2025, the government expected Greek inflation to slow to 2.2% in 2026 from 2.6% the previous year. Instead, the latest estimate puts it at 3.8%, after higher energy prices and renewed food-price pressures interrupted the anticipated slowdown.
That matters for government finances because VAT is charged as a percentage of a product’s price. If a shopping basket gets more expensive and consumption volumes don’t fall proportionately, the government collects more tax even without raising VAT rates.
The fiscal effect is substantial. Greece originally projected a 2026 primary budget surplus—excluding interest payments—of €7.21 billion, or 2.8% of gross domestic product. That estimate rose to €8.48 billion in April and now stands at €9.55 billion, or 3.6% of GDP. For 2027, Athens expects €77.88 billion in total tax revenue, including €30.58 billion from VAT. If VAT were to beat projections by a similar percentage again, receipts could exceed €32 billion.
That raises a politically awkward question: What should Greece do with recurring revenue surprises? So far, much of the response to cost-of-living pressures has involved targeted benefits, one-off payments and subsidies rather than broad, permanent reductions in taxation. Such transfers can direct money toward households most in need and are easier to adjust if fiscal conditions deteriorate.