Greece's plan to establish government-backed investment accounts for young children could create a new avenue for laundering illicit funds, as proposed rules would allow individuals unrelated to beneficiaries to transfer money without incurring gift taxes.
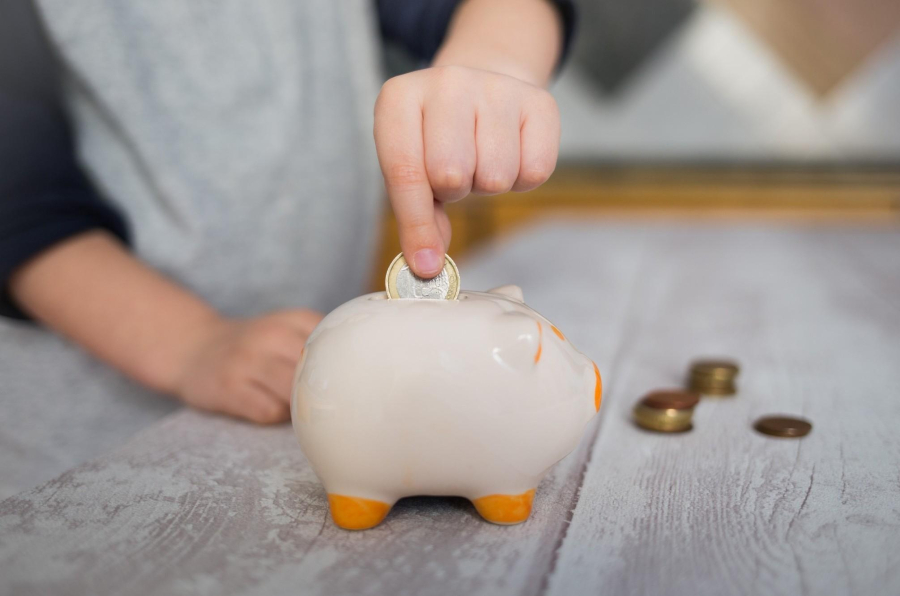
The initiative, included in draft legislation released by the Ministry of National Economy and Finance for public consultation until Nov. 1, is designed to encourage long-term savings by matching private contributions euro for euro.
But provisions allowing unrestricted participation by third-party contributors, combined with broad tax exemptions, raise questions about whether the scheme could be exploited to legitimize funds of questionable origin.
ΔΙΑΒΑΣΤΕ ΕΠΙΣΗΣ
Under the proposal, parents could open investment accounts for children younger than two, with the government matching contributions up to €1,200 annually.
Total private contributions would be capped at €10,000 per child each year, while accumulated funds would generally remain invested until the beneficiary turns 18.
The legislation explicitly permits contributions from any individual, regardless of family relationship. Crucially, these transfers would be exempt from gift and parental-transfer taxes, as well as certain tax rules that ordinarily require taxpayers to justify expenditures against their declared income.
The combination could create opportunities for individuals seeking to transfer money into tax-advantaged accounts without facing the same tax scrutiny that applies to conventional gifts.
The draft legislation doesn't establish a specific mechanism for cross-checking third-party contributions against contributors' declared earnings. That omission doesn't eliminate existing anti-money-laundering obligations or financial institutions' requirements to verify the origin of suspicious funds.
Nevertheless, questions remain about whether additional safeguards will be introduced before the legislation reaches Parliament.
The proposed accounts would offer four investment strategies, ranging from conservative to aggressive, allowing contributions to be invested in stocks, bonds, mutual funds and exchange-traded funds.
Families that don't select an investment strategy would automatically enter a capital-guaranteed product, with annual management costs capped at 0.5%.
The government would also increase its maximum annual contribution by 10% every five years.
For families contributing €100 monthly, combined private and public payments could accumulate to at least €43,200 over 18 years, excluding investment returns and fees.
While the program aims to build financial security for future generations, its tax exemptions and broad eligibility rules present a regulatory challenge.
The draft legislation remains open for public consultation before parliamentary consideration.